
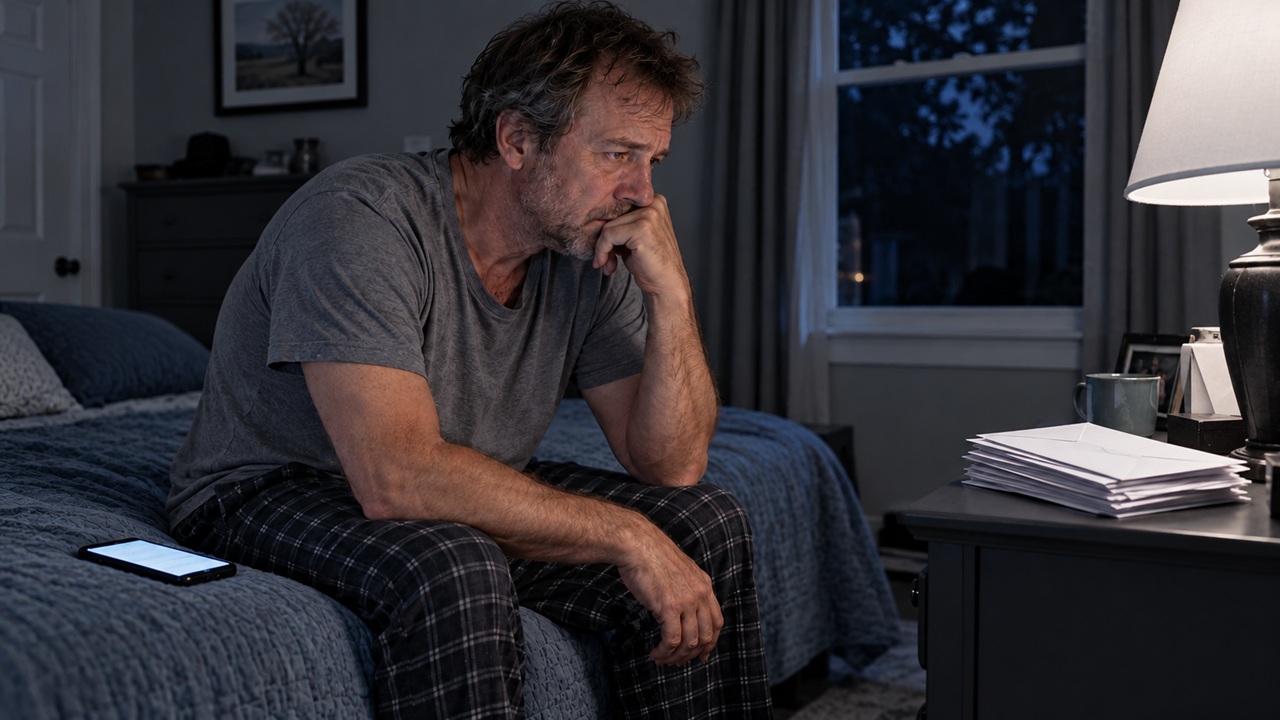
Debt Can Follow Someone Through the Entire Day
Debt can wear down South Carolina families long before they miss a payment or face a lawsuit. Unpaid bills, rising balances, and constant money decisions run in the background all day, taking up mental space that could go to work, family, and rest. On a recent episode of the Debt Sucks podcast, bankruptcy attorney Ben Matthews explained why that drain matters as much as the dollars.
Families tend to track what they owe and what it costs in interest. Far fewer think about what debt costs them in sleep, focus, and peace of mind. Practical steps can lower that cost for many families. But when debt has grown beyond what any budget can handle, a South Carolina bankruptcy lawyer can explain legal options that stop the collection calls and offer a real fresh start.
|
What to Know About the Energy Cost of Debt
|
What Is the Energy Cost of Debt?
Debt is usually measured with two numbers: how much is owed and the interest rate. But there's a third measure we call the "energy rate." It's the amount of mental and emotional energy a debt takes up every day, whether or not a payment is due. Two debts with the same balance can have very different energy rates.
A small medical bill that keeps showing up in the mail, a balance owed to a relative, or a credit card that gets a collection call every evening can weigh on someone far more than its size suggests. Each one becomes a recurring reminder, a decision to put off, or a source of guilt. Together, they create a constant hum of worry that's hard to turn off.
That hidden cost is easy to overlook because it doesn't show up on a statement. But it shapes how people sleep, how they treat the people around them, and how much energy they have left for work and the things they enjoy. Once people recognize it, they can start taking that energy back.
Signs Debt Is Draining Your Energy
Financial stress doesn't always look like a crisis. Often it shows up quietly in everyday life, and many people don't connect the dots to their debt. Some common warning signs include:
- Dreading the Mailbox or Phone: Avoiding mail, unknown callers, or bank apps because of what might be waiting there.
- Trouble Sleeping: Lying awake running through bills and due dates late at night.
- Trouble Focusing at Work: Money worries crowding out attention during the workday.
- Arguments at Home: Frequent tension with a spouse or partner over spending and bills.
- Putting Off Health Care: Skipping doctor visits or prescriptions to save money or avoid new bills.
- Feeling Stuck: Making payments every month while balances barely move.
These signs are more than inconveniences. Over months or years, they can take a real toll on health, relationships, and job performance. When debt is affecting daily life this much, it's worth looking closely at whether the current plan is working or whether a bigger solution is needed.
Get Your Debt Out of Your Head and Onto Paper
One of the simplest ways to lower the energy cost of debt is to write every debt down in one place. A single worksheet listing each creditor, balance, interest rate, minimum payment, and due date turns a cloud of worry into something concrete. Problems that feel endless when they're bouncing around in someone's head often look more manageable on a page.
That worksheet also makes patterns easier to see. It may show that a few high-interest cards are eating most of a paycheck, or that several small debts could be cleared quickly. It may reveal accounts close to being sent to collections. With the full picture in front of them, people can choose what to tackle first instead of reacting to whatever bill arrives next.
Sometimes the worksheet delivers a hard truth: the debt is bigger than the household's income can realistically handle. That's not a personal failure. It's important information. When the numbers simply don't add up, it may be time to talk with a bankruptcy attorney about options that budgeting alone can't provide.
Make Fewer Money Decisions Every Day
Every money decision uses up energy. Deciding which bill to pay, whether to make a purchase, or how to stretch a paycheck wears people down over time, a problem known as decision fatigue. Cutting down on the number of financial decisions made each day can free up a surprising amount of mental space.
Automation is one of the easiest ways to do that. Automatic payments for regular bills, like utilities or a car payment, remove the need to remember due dates. Simple personal money rules help too, such as waiting 48 hours before any purchase over a set amount. A rule makes the decision once, so it doesn't have to be made again every time.
We also suggest giving money a set weekly appointment. Instead of worrying about finances seven days a week, people can set aside one time each week to pay bills, check accounts, and review their plan. The rest of the week, money stays in its lane. That single habit can turn constant anxiety into a manageable routine.
Start With the Debts That Weigh on You Most
Standard advice often says to pay off the highest-interest debt first. That can save money, but it doesn't always lower stress the fastest. Some small debts carry an outsized energy rate, such as a bill that triggers daily collection calls or money owed to a friend. Paying those off first can free up instant mental space.
Clearing even one nagging debt creates a sense of progress that makes the next step easier. It also cuts the number of bills, calls, and reminders competing for attention each week. When people see results, they're more likely to stay with their plan instead of giving up when progress feels slow.
Focusing on one financial problem at a time matters too. Trying to fix everything at once often leads to burnout. Picking one target, finishing it, and then moving on builds momentum. If the list of problems keeps growing faster than it can be solved, though, that's usually a sign that a more powerful solution is needed.
Build a Buffer Against Small Emergencies
Many financial crises start small. A flat tire, a broken appliance, or a surprise medical bill can push someone to put the cost on a credit card or skip another payment. That one setback can set off late fees, higher interest, and missed bills, turning a minor problem into a full-blown financial fire.
An emergency fund absorbs those small hits before they spread. Even a few hundred dollars set aside can cover many common surprises without adding new debt. Building that fund with small automatic transfers from each paycheck can lower the energy cost of debt by removing the constant fear that one bad week could knock everything over.
For families already buried in debt, saving anything may feel impossible because every dollar is spoken for before it arrives. When debt payments leave no room for even a small cushion, a bankruptcy attorney can review whether legal options could free up money for the basics, including savings.
Cut the Microstress That Chips Away at You
Not all of debt's energy cost comes from big balances. Much of it comes from what Ben Matthews calls microstress, the small reminders and temptations that pile up throughout the day. Shopping app alerts, sales emails, and forgotten subscriptions quietly drain both money and attention without people realizing it.
Canceling unused subscriptions is a quick win. Streaming services, apps, and memberships that renew automatically can add up to a surprising amount each month. Turning off shopping notifications and unsubscribing from promotional emails reduces both the urge to spend and the constant pull on attention.
Simplifying accounts helps as well. Fewer credit cards, bank accounts, and payment apps mean fewer balances to track and fewer chances for something to slip. A simpler setup makes the weekly money appointment easier and leaves less to worry about the rest of the week.
Here's how these steps fit together and what each one does to lower the energy cost of debt.
| Step | What It Looks Like | How It Lowers the Energy Cost |
|---|---|---|
| Measure each debt's energy rate | Ranking debts by how much worry they cause | Shows which problems drain the most peace of mind |
| Put debt on one worksheet | Listing every creditor, balance, rate, and due date | Turns vague worry into a clear plan |
| Automate and set money rules | Automatic bill payments and simple spending rules | Cuts down on daily decision fatigue |
| Schedule a weekly money appointment | One set time each week to handle bills and accounts | Keeps money worries from filling every day |
| Pay off high-stress debts first | Clearing the bills that cause the most frustration | Frees up mental space and builds momentum |
| Build an emergency fund | Small automatic transfers into savings | Keeps small setbacks from becoming new debt |
| Cut microstress | Canceling subscriptions and turning off shopping alerts | Removes constant small drains on money and attention |
When the Energy Cost Is Too High to Fix With a Budget
For many South Carolina families, the problem isn't a lack of organization or discipline. It's that the debt has grown bigger than their income. Medical bills, job loss, divorce, or an injury can leave people facing balances they could never realistically repay, no matter how carefully they budget. In those cases, the energy cost of debt keeps climbing month after month.
Bankruptcy is a legal tool built for exactly those situations. Chapter 7 can wipe out many types of unsecured debt, such as credit cards and medical bills. Chapter 13 sets up a court-approved repayment plan that can help people catch up on a mortgage or car loan while keeping their property. Once a case is filed, a court order called the automatic stay generally stops most collection calls, lawsuits, wage garnishments, and foreclosures.
Many people put off talking to a bankruptcy attorney because they feel embarrassed or think it means giving up. In reality, it can be one of the most responsible steps someone takes to protect their family and their future. The sooner someone gets advice, the more options they usually have, especially before a foreclosure or garnishment moves forward.
How the Energy Cost of Debt Can Build Over Time
Imagine a couple in Columbia juggling four credit cards, a car payment, and medical bills from a recent surgery. They make minimum payments every month, but the balances barely move. Collection calls come in daily, and they argue about money most nights. Both are exhausted and distracted at work.
They list every debt on one worksheet, cancel a few subscriptions, and set up automatic payments for their regular bills. Those steps bring some relief. But the worksheet also shows that their minimum payments eat up nearly half their take-home pay, and the medical debt alone would take years to pay off.
After talking with a bankruptcy attorney, they learn that a Chapter 7 or Chapter 13 filing could stop the collection calls and eliminate or restructure much of what they owe. Instead of spending years treading water, they can focus on rebuilding their savings and getting their energy back. The worksheet that started as a budgeting tool ended up pointing them toward a real fresh start.
Debt Sucks, but It Doesn't Have to Run Your Life
The hidden energy cost of debt takes a toll on health, relationships, and quality of life. Practical steps can lighten the load, but when debt has grown beyond what any budget can handle, it's time to look at bigger solutions. South Carolina families deserve honest advice about every option available to them.
At Benjamin R. Matthews & Associates, LLC, attorney Ben Matthews and his team have handled thousands of cases since 1985, helping hard-working South Carolinians meet life's financial challenges. As Ben puts it, "We're not those lawyers on TV selling legal services like a fleet of cars." Clients talk to the attorneys directly, and every case gets personal attention from our offices in Columbia and Rock Hill.
We offer a free, confidential consultation to everyone who calls. Talk with our team today to find out whether bankruptcy could stop the stress, help you start over, and give you back the energy debt has been taking.
"Had my first consultation today via phone it was a quick easy pain free 20ish minutes the gentleman was friendly and understanding and explained any questions I had they also offer payment plans." - K.J., ⭐⭐⭐⭐⭐